

Philippines services
Here are 9 common mistakes that businesses encounter when dealing with their accounting, bookkeeping and finance functions. We also identify what companies can do to make sure that these mistakes don’t happen!
People say it’s good to learn from your mistakes.
We think it’s a much better idea to identify where mistakes can arise and then put in place processes and systems to make sure that these mistakes don’t ever happen.
So that’s what we have done!
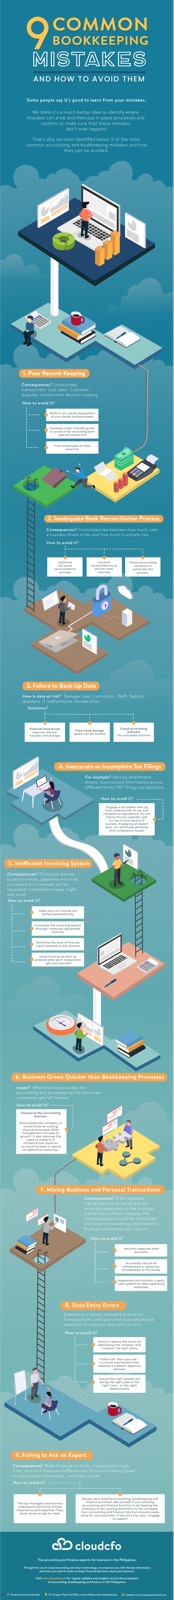
Outlined below are 9 common mistakes that businesses encounter when dealing with their accounting, bookkeeping and finance functions.
We have also gone one step further – we explain what companies can do to make sure that these mistakes don’t happen.
So let’s get started!
When a business does not keep on top of its record-keeping activities, a risk arises of having unrecorded or improperly recorded transactions on their books of accounts.
This is unhelpful from a commercial perspective as it can lead to supporting documents such as invoices, receipts, billing statements, purchase orders, etc, being incorrectly completed, submitted or stored.
It is also unhelpful from a compliance and regulatory perspective. During a tax audit, for example, the Bureau of Internal Revenue, or BIR, might request the company to submit certain supporting documents. If the accounting records are incomplete or disorganised, it is going to be very difficult to comply with this important request from the tax authorities.
Other potential consequences of poor record-keeping include:
Don’t worry though – all is not lost! Here’s a step-by-step guide to help improve your company’s record-keeping processes:
Bank reconciliation is the process of matching bank records with cash records to identify unrecorded transactions or differences within your accounts and then reconciling them. It also helps to determine how much cash a business has to hand.
We identified Bank reconciliations as a key accounting terms in our recent article on the important accounting and bookkeeping concepts that managers and owners in the Philippines should know.
A common problem for businesses who fail to perform bank reconciliations involves outstanding checks. Outstanding checks are checks issued by the business but which have not yet been presented for payment by the payee.
For example, if a company has P250,000 in the bank, but has outstanding checks issued to the value of P100,000, the company has much less money than its cash balance might indicate. Failing to perform a bank reconciliation may mean that this information won’t be considered!
2 tips to simplify and add value to your bank reconciliation process:
Check out our previous article on Bank Reconciliations: Why it matters for more in-depth analysis.
Backing-up data is important! Especially when a company holds information relating to customers, suppliers, tax documents, employees and key financial information.
Whether your company performs its accounting and bookkeeping functions via the traditional approach using paper and hard copies or online through cloud accounting and online accounting solutions, a company must be confident that its data is secure.
Data can be lost or corrupted in many ways. There are natural disasters such as earthquakes, floods or storms, particularly in countries such as the Philippines. Other types of disasters can include malfunctioning of hard disks, laptops or flash drives.
Here are just some ways of ensuring your bookkeeping data is backed up and secure:
Taxation, taxation, taxation – a key consideration in every accounting and bookkeeping process!
In short, companies are required to report their income and expenses to the government or BIR in order to pay the necessary taxes.
There are penalties for companies who fail to submit tax returns or who make errors when submitting their tax returns. Reasons for this might include human error, lack of resources to manage the accounting function or a lack of specialised accountancy knowledge and expertise when it comes to tax laws, regulations and compliance.
Here are some common tax filing errors:
So how can companies avoid submitting inaccurate or incomplete tax filings?
The invoice process involves issuing an invoice to clients as proof that a sales transaction has occurred. It is always helpful to invoice clients on time so the company can receive payment without delay.
As clients use invoices to match their payments, failing to issue an invoice generally means that the particular payment can’t be processed. This might impact sales or revenue for a particular month, quarter or year!y.
In other words, an efficient and time-conscious invoicing process can significantly improve a company’s cash flow by speeding up the collections process.
So, how do you create an efficient invoicing process? Here’s how:
There can be no greater sense of accomplishment for a business owner than to see their own business taking off.
Sales increasing every month, staff numbers growing, new clients, new leads and new projects!
However hard it might be, owners must ensure that certain business functions also grow with the business. In particular, the accounting and bookkeeping processes.
If, for example, your accountant is asking for more and more time to provide you with key financial information that you have requested, it could be a sign that your bookkeeping processes have not grown as fast as your business and require review.
Why is it that sometimes bookkeeping and accounting functions don’t grow when a business scales?
So how can a company ensure its bookkeeping capabilities keep up with the business during a period of growth?
Of course, the best approach is to get it right from the very start! At the early stages of a company’s journey, it can be really valuable to implement processes, systems and resources that enable scalability in the future. This requires a seamless integration and collaboration between the different departments in a company and the accounting function from the outset.
However, accounting and bookkeeping might not always be at the top of the priority list when a company is starting out. If robust processes have not been implemented already, it can be an excellent solution to outsource your accounting services during a period of growth.
During this time, a business can rely on an outsourced finance and accounting service provider to take over and help manage this specialised function. The outsourcing firm is the one responsible for engaging the necessary resources.
The client company does not need to bear the burden of hiring, training and providing office equipment. The company also benefits from market expertise and knowledge!
We believe that a company should, at a minimum, always look for one key attribute from an outsourcing provider: hire someone who aims to understand your business.
A company might also consider hiring an outsourced Chief Financial Officer to get their accounting, bookkeeping and finance function into shape.
Sometimes, businesses don’t follow the ‘separate entity concept’. The separate entity concept requires that the owner remains a separate entity or personality from the business entity at all times.
In short, the personal transactions of an owner should always be recorded separately from the transactions of the business.
Two examples below of where this might arise:
So, how do you ensure your business and personal spending remain separate? Here’s how:
Data entry is always susceptible to human error.
While a data entry error may sometimes only involve a single number or letter, the consequences can be significant. This is particularly the case when dealing with the accounts and finances of a company.
Here are some of the most common data entry errors:
a. Transposition – unintended switching of two or three digits in a particular entry
b. Omission – Not recording an amount or transaction
c. Duplication – Recording an entry twice in the same place
Data entry errors jeopardize the accuracy of final data. An omission or incorrect entry of a sale of P10,000 could result in a tax filing error, an incorrect update of a customer account, a loss in revenue and a distortion of key company metrics. All from just one single error!
So how to avoid or minimize data entry errors?
A business should know its expertise and know the limits of its expertise.
An owner or manager may have significant experience in operations but might have little experience of HR or a CEO might have an excellent grasp on all finance matters but have difficulty understanding technology.
Where companies or owners attempt to manage the entire accounting and bookkeeping functions themselves, it can create serious issues if they don’t have the necessary expertise and knowledge. They might not even know some of the most basic accounting concepts that all owners should know!
This issue can be a significant challenge in the Philippines where the tax compliance and regulatory system is so complex.
What kind of issues might arise?
We say let the experts help. That is what we are here for.
CloudCfo can help companies, managers and owners avoid all of these common bookkeeping mistakes. As a trusted provider of accounting and bookkeeping services in the Philippines, we offer our services across the entire range of bookkeeping, tax and regulatory matters.
We want to fully understand the business of our clients. This enables us to provide the best possible accounting, bookkeeping and tax services to companies in the Philippines. It also helps ensure that our clients are well positioned when they start to scale.
Visit us at cloudcfo.ph or contact us at hello@cloudcfo.ph for more information on how we can support your business here in the Philippines.
Get clean, up-to-date books every month from a dedicated bookkeeping team working in Xero or QuickBooks.
Explore this service →or book a free consultation

Questions about how this affects your business? Our team replies within one business day.




























































